Underpaid or Denied Hurricane Claims in Pensacola?
Hurricane Insurance Claim Help for Pensacola, Pace, Milton, Navarre, and Escambia and Santa Rosa County, Florida.
Already Received an Insurance Payment That Doesn't Cover Your Hurricane Damage?
Your insurance company’s estimate may not reflect the full extent of the damage or the repairs needed to restore your property.
If your hurricane insurance claim was underpaid, partially denied, or denied altogether, Cloud 9 Claims Public Adjusters can help you evaluate the damage, review your insurance company’s estimate, and prepare supporting documentation for a fair claim settlement.
We represent policyholders—not insurance companies.
Our Florida-licensed public adjusters serve homeowners with hurricane insurance claims in Pensacola, Pace, Milton, Navarre, and surrounding Florida Panhandle communities.
Hurricane Property Damage?
Request Your Insurance Claim Review
Is Your Hurricane Insurance Settlement Enough to Repair Your Home?
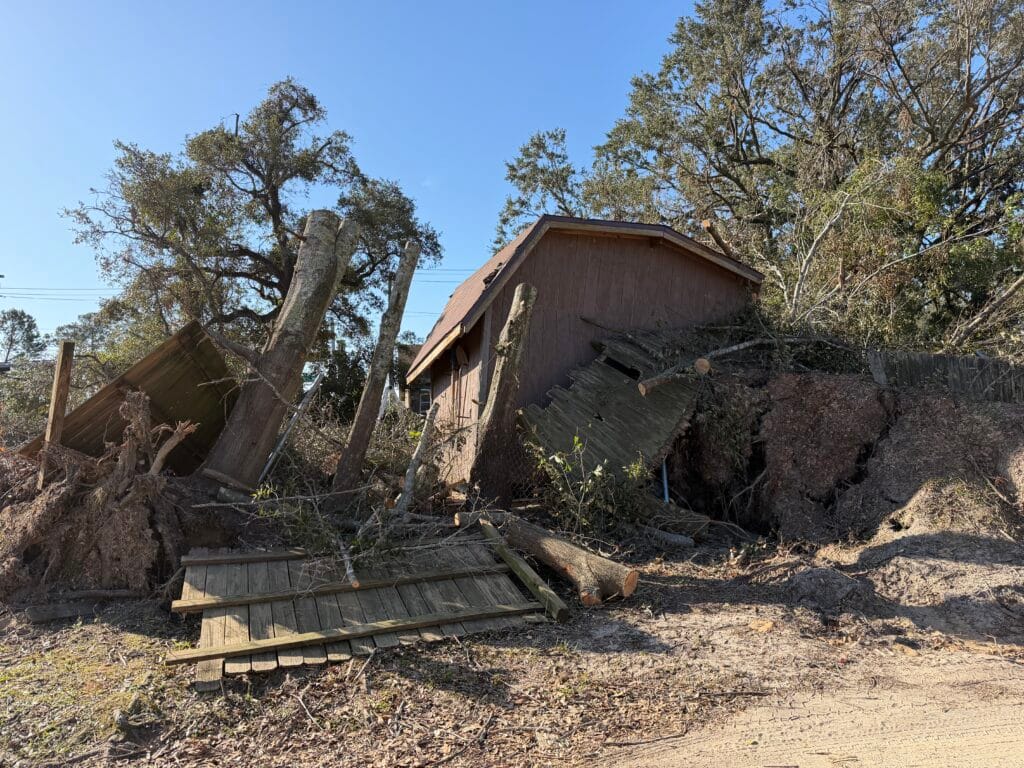
After a hurricane, homeowners may discover that the insurance company’s estimate differs significantly from the actual cost of repairing their property.
An insurance estimate may omit damaged materials, underestimate repair quantities, or fail to address work necessary to complete covered repairs.
Cloud 9 Claims helps homeowners identify and document potential differences between the insurance company’s assessment and the damage to their property.
COMMON HURRICANE CLAIM PROBLEMS WE REVIEW
After a hurricane, homeowners may discover that the insurance company’s estimate differs significantly from the actual cost of repairing their property. An insurance estimate may omit damaged materials, underestimate repair quantities, or fail to address work necessary to complete covered repairs.
Cloud 9 Claims helps homeowners identify and document potential differences between the insurance company’s assessment and the damage to their property.
UNDERPAID ROOF DAMAGE CLAIMS
Did your insurance company approve limited roof repairs when your contractor believes additional work is necessary?
We review the damage documentation, repair scope, material compatibility, applicable building requirements, and relevant policy provisions.
DENIED HURRICANE DAMAGE CLAIMS
Has your insurer denied damage based on wear and tear, deterioration, maintenance, or another exclusion?
We review the insurer’s explanation and available damage evidence to evaluate whether additional factual documentation may support reconsideration.
MISSING INTERIOR WATER DAMAGE
Wind-related openings can allow rainwater to enter ceilings, walls, insulation, flooring, and other building materials.
We review available inspection findings, photographs, moisture documentation, and repair estimates to identify potentially overlooked damage.
INCOMPLETE INSURANCE ESTIMATES
Insurance company estimates and contractor estimates may differ because of missing line items, repair methods, material quantities, labor operations, or pricing.
Our public adjusters evaluate these differences and help prepare detailed supporting estimates when appropriate.
HURRICANE DEDUCTIBLES & DEPRECIATION
Hurricane deductibles, depreciation, roof payment provisions, and policy endorsements can affect the amount an insurer pays.
We review how these provisions have been applied to the claim and identify items that may require further clarification.
SUPPLEMENTAL HURRICANE CLAIMS
Additional damage or repair requirements may become apparent after the insurance company’s initial inspection.
When supported by the facts and policy, a supplemental claim may be appropriate to document additional covered repair costs.
Already received an estimate or denial letter? Contact us for a second opinion.
Your Insurance Company Has an Adjuster. You Can Have One Too.
When you file a hurricane insurance claim, the insurance company assigns an adjuster to investigate and evaluate the loss on its behalf. A licensed public adjuster represents the policyholder in the preparation, presentation, and adjustment of property insurance claims.
Steven Hayden
Florida Licensed Public Adjuster #A114261
Meet Your Public Adjuster
At Cloud 9 Claims Public Adjusters, our focus is helping Florida property owners navigate the insurance claim process with confidence.
With 9 years of experience in property insurance claims, Steven brings hands-on knowledge of hurricane damage assessments, insurance estimating, and claim documentation.
From reviewing an underpaid settlement to preparing a detailed supplemental claim, our approach emphasizes accurate documentation, clear communication, and policyholder-focused representation.
Meet Your Public Adjuster
With 7 years of experience in property insurance adjusting and a background as a former Sheriff’s Deputy, Renzo brings professionalism, integrity, and attention to detail to every claim he handles.
As a member of Cloud 9 Claims Public Adjusters, Renzo is dedicated to helping Florida homeowners and business owners navigate the insurance claim process with confidence. He specializes in thoroughly evaluating property damage, identifying overlooked repairs, and preparing detailed documentation to support fair insurance claim settlements.
His background in law enforcement reinforces his commitment to accountability, clear communication, and serving others. Whether assisting with hurricane damage, water losses, or underpaid insurance claims, Renzo takes a personalized, policyholder-focused approach to every claim.
Renzo Caamano
Florida Licensed Public Adjuster #W550738

Is Your Hurricane Insurance Claim Estimate Missing Important Repairs?
An insurance company’s initial estimate may not include every repair necessary to address covered hurricane damage. Cloud 9 Claims Public Adjusters reviews insurance estimates, property damage documentation, and contractor repair scopes to identify potential discrepancies.
Here are some of the items we evaluate:
ROOF DAMAGE
Are all damaged roofing components included? Does the estimate address necessary removal, replacement materials, flashing, underlayment, and applicable repair requirements?
DEPRECIATION AND POLICY PROVISIONS
We review how deductibles, depreciation, and applicable policy conditions affect the claim payment.
INTERIOR WATER DAMAGE
Does the estimate address documented damage to ceilings, walls, insulation, flooring, cabinetry, and other affected materials?
MISSING REPAIR ITEMS
Are necessary labor operations, material quantities, access requirements, and associated repair work accurately reflected?
CONTRACTOR ESTIMATE DIFFERENCES
Does your contractor’s estimate include additional repairs or different methods? We compare the estimates to identify and document relevant differences.
Your Insurance Estimate Deserves a Second Look
If your hurricane settlement doesn’t appear sufficient to complete covered repairs, Cloud 9 Claims can help evaluate the documentation and determine whether additional claim information may be appropriate.
What Our Clients Say
Posted on Google
 Keith Burchett434 days ago
Trustindex verifies that the original source of the review is Google.
I am very pleased with cloud 9 claims! Steven and Renzo were very responsive and stayed on top of my claim. They touched base with me to keep me informed, always took my calls when I had questions and explained all process steps. I will use them in all future needs. It is good to have a partner and we would give Cloud 9 our highest recommendationPosted on Google Nicole S665 days ago“It was a pleasure working with this team, (Renzo and Steven). From the very beginning, they demonstrated professionalism, expertise, and a genuine commitment to excellence. Every step of the process was seamless, and they went above and beyond to ensure our needs were met. We are grateful for the attention to detail and personalized care. I highly recommend their services to anyone looking for top-notch quality and exceptional customer support.”Posted on Google
 Carol DeYoung943 days agoAfter Hurricane Ian, Cloud 9 proved to be a beacon of hope in a sea of frustration with my insurance company. Despite my legitimate claim, the insurer seemed more interested in obstructing than assisting me. Cloud 9 stepped in, demystifying the claims process and advocating on my behalf. Thanks to their tireless efforts, I avoided the stress of mediation and litigation, securing the coverage I deserved. I can't sing their praises enough - Cloud 9 truly transformed a daunting experience into a triumphant one!Load moreVerified by TrustindexTrustindex verified badge is the Universal Symbol of Trust. Only the greatest companies can get the verified badge who has a review score above 4.5, based on customer reviews over the past 12 months. Read more

Our Three-Step Hurricane Claim Review Process
Step 1 — Review Your Insurance Estimate or Denial
We begin by discussing your concerns and reviewing available claim documents, including the insurance company’s estimate, settlement letter, denial explanation, photographs, and contractor estimates. This initial review helps determine whether additional evaluation may be appropriate.
Step 2 — Evaluate the Damage and Repair Scope
When appropriate, we arrange an on-site inspection of your Pensacola-area property. Our public adjusters evaluate the available evidence, inspect reported damage, and review differences between the insurance company’s estimate and the documented repair scope.
Step 3 — Prepare and Present Supporting Documentation
When additional covered damage or repair costs are supported, Cloud 9 Claims assists with preparing detailed estimates, photographs, and supporting claim information. We communicate with the insurance company as authorized and assist in pursuing a fair, properly documented settlement under the applicable policy.
Why Homeowners Choose Cloud 9 Claims for Underpaid Hurricane Insurance Claims
Experience and Thorough Documentation Matter
When your hurricane insurance settlement does not appear sufficient to repair your property, selecting a public adjuster involves more than finding the closest office. You want an experienced professional who understands property damage, insurance estimating, repair requirements, and the documentation needed to present a claim.
Policyholder-focused representation. We represent your interests, not the insurance company’s.
Detailed damage evaluations. We review the reported loss, available documentation, and repair scope.
Accurate repair estimating. We identify and document potentially missing or underestimated repair operations.
Experience with hurricane claims. Our team has assisted Florida property owners with hurricane-related property damage and insurance claim disputes.
Professional claim communication. We assist with claim preparation and insurer communications within the scope of our Florida public adjusting license.
Complimentary initial claim reviews. We help you understand whether additional claim evaluation may be appropriate.
For more information on this storm, visit our Hurricane Isaias Claims in Florida page.
Hurricane Insurance Claim Assistance in Pensacola, Pace, Milton & Navarre
Serving homeowners throughout Pensacola, Pace, Milton, Navarre, Escambia County & Santa Rosa County.
Pensacola Hurricane Insurance Claim Help
If your Pensacola home sustained hurricane damage and your insurance settlement appears insufficient, Cloud 9 Claims can help review the damage assessment and claim documentation.
We assist with underpaid roof claims, disputed wind damage, interior water intrusion, incomplete repair estimates, and denied hurricane damage claims.
Our service area includes Pensacola, Pensacola Beach, Perdido Key, and surrounding Escambia County communities.
Pace Hurricane Insurance Claim Help
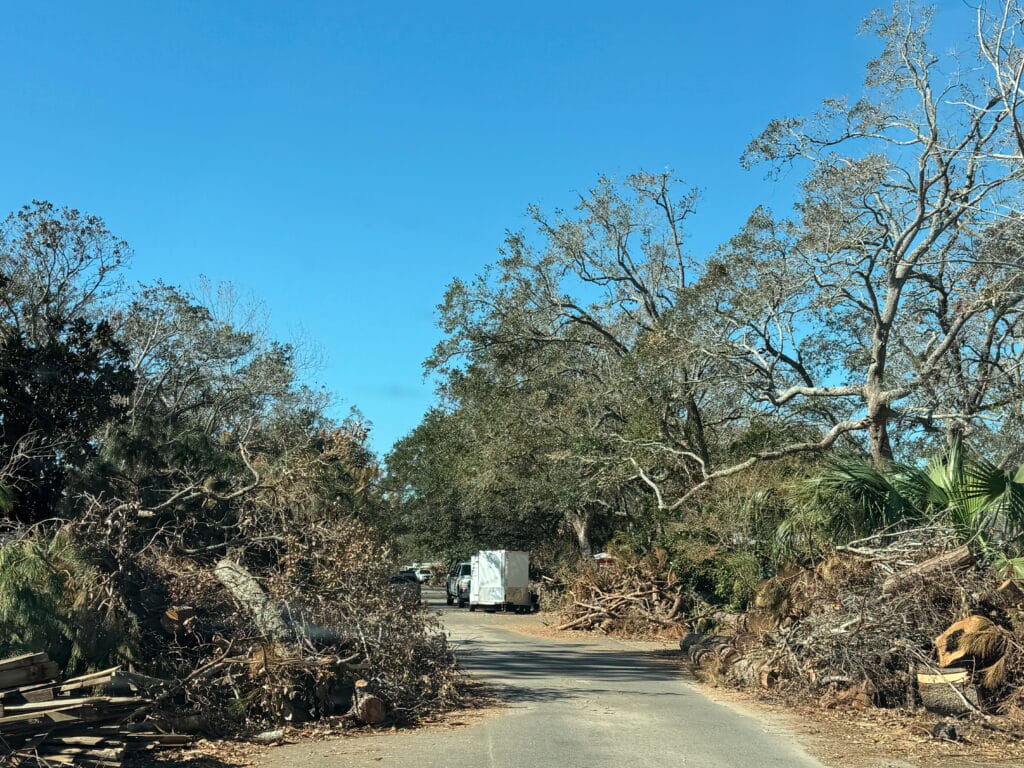
Pace homeowners may experience hurricane damage involving roofing materials, exterior building components, fallen-tree impacts, and interior water intrusion.
When an insurance company’s estimate does not appear to address the documented damage, we can review the claim and assist with preparing additional supporting information.
Milton Hurricane Insurance Claim Help
Cloud 9 Claims assists Milton homeowners with hurricane insurance settlement reviews, disputed roof and wind damage, incomplete repair scopes, and supplemental claim documentation.
Our focus is on identifying and documenting potentially overlooked covered repairs.
Navarre Hurricane Insurance Claim Help
Navarre and Navarre Beach homeowners may face hurricane-related roof damage, exterior building damage, wind-driven rain intrusion, and disputes involving the extent or cause of damage.
We assist with evaluating the insurer’s damage assessment and preparing supporting claim documentation when appropriate.
Underpaid or Denied Hurricane Claim? Let's Review It.
Your insurance company’s estimate may not reflect all the covered damage to your property.
Serving Pensacola, Pace, Milton, & Navarre.
Frequently Asked Questions About Underpaid Hurricane Claims in Pensacola
Can I hire a public adjuster after my insurance company has already paid my hurricane claim?
Generally, yes. Receiving an insurance payment does not automatically prevent a homeowner from seeking consideration of additional covered damage. Applicable deadlines, settlement agreements, and policy provisions should be reviewed.
What should I do if my hurricane insurance claim was denied?
Keep the written denial explanation, your policy, photographs, estimates, and claim correspondence. A licensed public adjuster can evaluate damage documentation and estimating issues. Disputed legal coverage questions may require an insurance attorney.
What if my contractor's estimate is much higher than the insurance company's estimate?
The estimates should be compared to identify differences in quantities, repair methods, material pricing, labor operations, and the scope of covered damage. A higher contractor estimate alone does not establish an insurance underpayment.
Can a public adjuster help with an underpaid hurricane roof claim?
Yes. A licensed public adjuster can evaluate roof damage documentation, repair estimates, and claim information to help determine whether additional supporting documentation is appropriate.
Can Cloud 9 Claims inspect my home in Pace, Milton, or Navarre?
Yes. Cloud 9 Claims can assist homeowners throughout these Panhandle Florida communities.
How much does a hurricane claim review cost?
Cloud 9 Claims offers a complimentary initial claim review. If you choose to retain our public adjusting services, we explain the applicable written agreement and fees before proceeding.
Is there a deadline to dispute an underpaid hurricane insurance claim?
Potential deadlines depend on the policy, date of loss, claim history, and applicable Florida law. Because deadlines can affect available options, homeowners should seek a timely review and consult an insurance attorney when legal rights or deadlines are disputed.